Running a business in Canada means taking risks. However, some risks are avoidable, especially when they involve your house, your savings, or your family’s financial security.
Many small business owners never stop to ask a simple question: is my business structure actually protecting me? This article answers that question directly, using plain language and practical steps.
TL;DR: Key Facts on Business Structure and Asset Protection
- Incorporating generally separates your personal assets from business debts, but only if you maintain proper corporate formalities.
- Sole proprietorships and general partnerships offer no legal separation. Your personal assets, including your home, are at risk.
- Courts can still “pierce the corporate veil” and go after your personal assets if you mix funds, commit fraud, or ignore corporate rules.
- Asset protection is not a one-time event. As a result, it requires ongoing maintenance as your business grows.
Table of Contents
- Does Incorporating Protect Personal Assets in Canada?
- What Is Asset Protection Planning?
- What Is the Biggest Risk of a Sole Proprietorship in Canada?
- Partnership Liability Risks in Canada
- Business Structure Comparison: Sole Proprietorship vs Partnership vs Incorporation
- Can a Court Pierce the Corporate Veil in Canada?
- How Do You Maintain Corporate Veil Protection as Your Business Grows?
- When Should You Incorporate Your Business in Canada?
- What Is the Best Business Structure for Asset Protection in Canada?
- Asset Protection Strategies for Incorporated Business Owners
- Manager’s Checklist: Protecting Your Personal Assets
- Frequently Asked Questions
- Key Takeaways
Does Incorporating Protect Personal Assets in Canada?
Yes, incorporating in Canada generally protects your personal assets. However, this protection only holds if you keep your business and personal finances separate and follow corporate formalities.
When you incorporate, you create a new legal entity. This entity is separate from you as a person. Consequently, if the business is sued or cannot pay its debts, creditors typically cannot touch your house, car, or personal bank account.
This concept is often called the “corporate veil.” It acts like a legal wall between your business and your personal life. On the other hand, this wall is not indestructible. Courts can look through it under specific conditions, which we cover later in this article.
For Canadian entrepreneurs comparing options, it helps to know that Canada does not have an LLC (Limited Liability Company) structure like the United States. Instead, Canadian business owners typically choose between a sole proprietorship, a partnership, or incorporation (federally or provincially). Some owners also use a holding company for extra protection, which we will explain further below.
What Is Asset Protection Planning?
Asset protection planning means organizing your business and personal finances to legally shield your wealth from business risks. It involves choosing the right structure, insurance, and financial habits before a problem happens, not after.
Many business owners think about asset protection only after a lawsuit or debt collection notice arrives. Unfortunately, by that point, options are limited. Planning ahead, therefore, gives you far more tools to work with.
Good asset protection planning usually includes several layers. For example, it might combine incorporation, proper insurance coverage, separate bank accounts, and clear contracts with clients and suppliers. In addition, some business owners use trusts or holding companies to add another layer of separation between operating risks and personal or accumulated wealth.
What Is the Biggest Risk of a Sole Proprietorship in Canada?
The biggest risk of a sole proprietorship in Canada is unlimited personal liability. If your business owes money or gets sued, creditors can pursue your personal assets, including your home, savings, and vehicle.
A sole proprietorship is the simplest business structure in Canada. Legally, there is no difference between you and your business. As a result, every contract you sign and every debt you take on is your personal responsibility.
Consider a common example. A contractor operates as a sole proprietor and a client sues over faulty work. If the court rules against the contractor, personal assets can be seized to pay the judgment. Insurance may help, but it does not always cover every claim.
Many small business owners choose sole proprietorship because it is cheap and easy to set up. However, this convenience comes at a real cost: your personal financial safety net disappears.
Partnership Liability Risks in Canada
General partnerships carry a unique danger. Each partner can be held personally responsible for the actions of the other partners, not just their own.
This is sometimes called “joint and several liability.” In plain terms, if your business partner signs a bad contract or makes a costly mistake, you could be on the hook for the entire debt. This holds true even if you had no idea the decision was being made.
Consequently, partnerships require a high level of trust and clear legal agreements. A well-drafted partnership agreement can help define responsibilities. However, it typically cannot fully eliminate liability to outside creditors or lawsuits.
Some Canadian provinces allow Limited Partnerships (LPs) or Limited Liability Partnerships (LLPs) for certain professions, such as law or accounting firms. These structures offer more protection for limited partners. Nonetheless, general partners in these arrangements often still face full personal liability.
Sole Proprietorship vs Incorporation in Canada: Tax and Liability Comparison
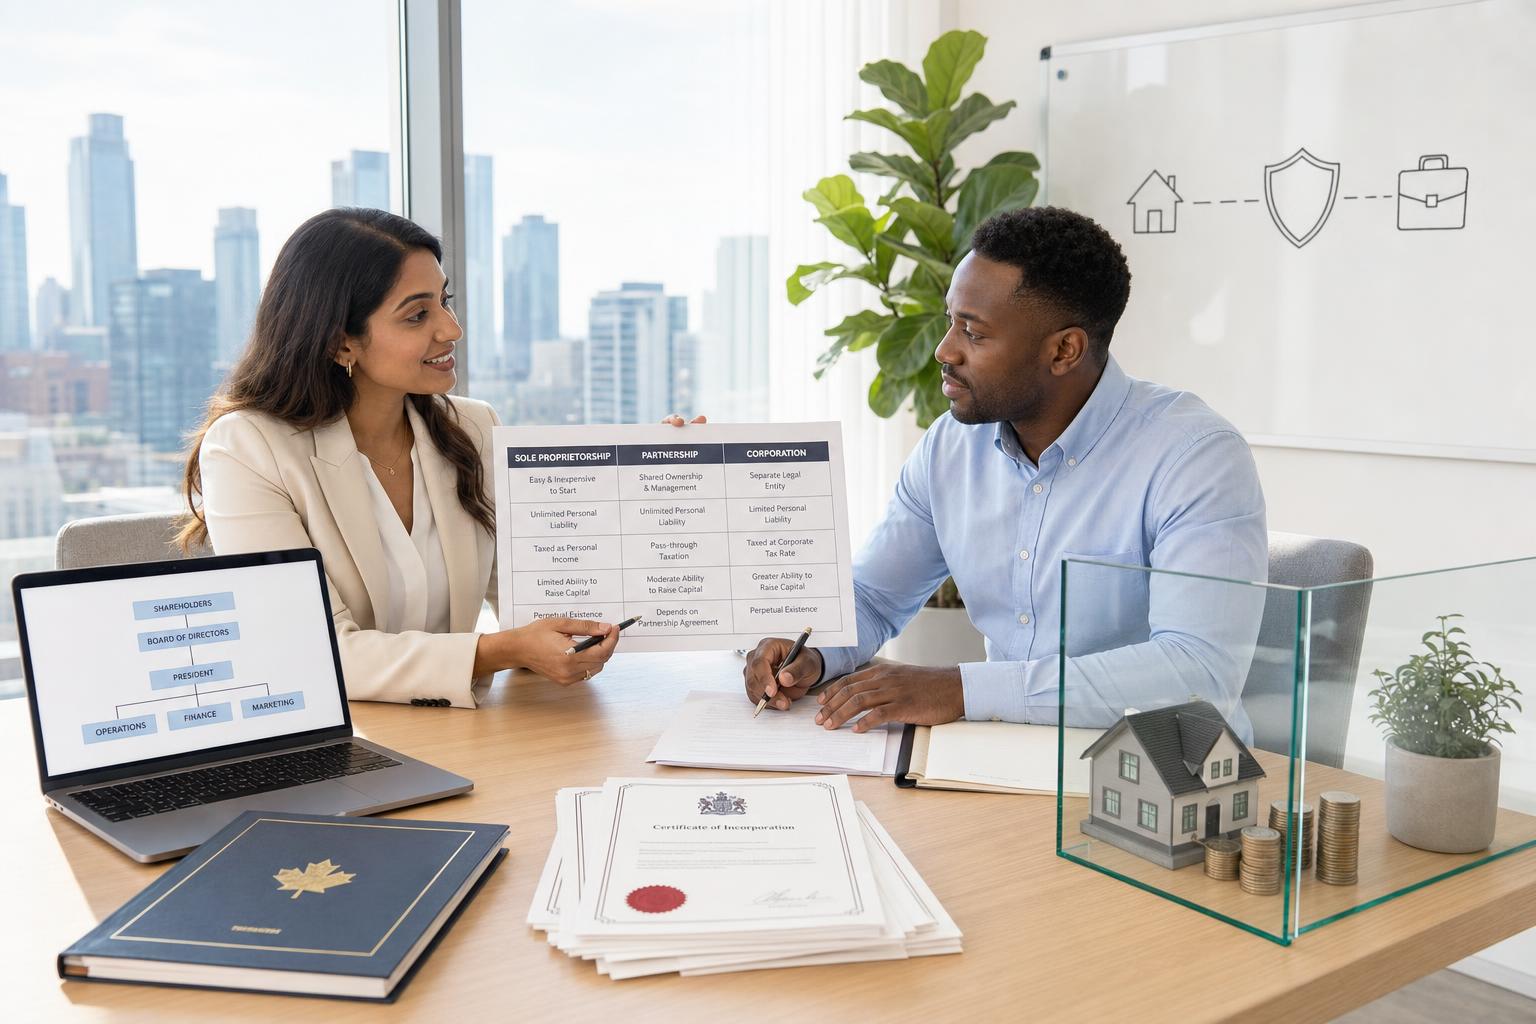
Choosing between a sole proprietorship, a partnership, and a corporation affects both your tax bill and your personal risk. The table below breaks down the main differences.
| Feature | Sole Proprietorship | Partnership | Incorporation |
|---|---|---|---|
| Personal Liability | Unlimited | Unlimited (joint and several) | Limited, if formalities are followed |
| Setup Cost | Low | Low to moderate | Higher (legal and filing fees) |
| Tax Treatment | Taxed as personal income | Taxed as personal income for each partner | Taxed at corporate rates; may allow income splitting |
| Ongoing Compliance | Minimal | Moderate (partnership agreement) | Higher (annual filings, corporate records) |
| Best For | Very small, low-risk side businesses | Professional practices with trusted partners | Growing businesses with real liability exposure |
As the table shows, incorporation generally offers stronger protection. However, it also demands more paperwork and ongoing attention. In contrast, a sole proprietorship is simple, but that simplicity leaves you exposed.
Can a Court Pierce the Corporate Veil in Canada?
Yes, Canadian courts can pierce the corporate veil in specific situations. This usually happens when a business owner uses the corporation to commit fraud, mixes personal and business funds, or ignores basic corporate formalities.
“Piercing the corporate veil” means a court decides to ignore the legal separation between you and your corporation. When this happens, your personal assets become fair game for creditors or lawsuits.
Courts do not take this step lightly. Typically, they look for clear evidence of misuse. Common triggers include the following:
- Commingling funds: Using the business bank account to pay personal bills, or vice versa.
- Undercapitalization: Starting a high-risk business with almost no funding or insurance.
- Fraud or misrepresentation: Using the corporation to deceive creditors, customers, or the government.
- Ignoring corporate formalities: Failing to hold proper records, file annual returns, or keep meeting minutes.
- Personal guarantees: Signing a personal guarantee on a loan or lease, which directly exposes personal assets regardless of incorporation.
When we work through asset protection reviews with incorporated business owners, we often find that personal guarantees are the most overlooked risk. Many owners assume incorporation covers everything, yet a signed guarantee on a commercial lease can undo that protection instantly.
How Do You Maintain Corporate Veil Protection as Your Business Grows?
Maintaining corporate veil protection requires ongoing discipline. You must keep separate finances, file required documents on time, and treat your corporation as a distinct legal entity in every decision.
Incorporation is not a “set it and forget it” solution. As your business grows, so does the complexity of staying protected. Here are the core habits to build:
- Keep separate bank accounts. Never pay personal expenses directly from the business account.
- Pay yourself properly, through salary or dividends, rather than withdrawing cash informally.
- File annual corporate returns with Corporations Canada or your provincial registry, depending on where you incorporated.
- Keep organized minute books, including director resolutions and shareholder records.
- Sign contracts as the corporation, using your official business name and title, not your personal name.
- Maintain adequate insurance, since undercapitalization can be used as evidence against you in court.
- Review your structure regularly, especially after major growth, new partners, or new revenue streams.
As your company scales, consider adding a holding company above your operating business. This structure can separate accumulated profits and assets from the operating risks of daily business activity. Therefore, if the operating company faces a lawsuit, assets held safely in the holding company are generally harder to reach.
When Should You Incorporate Your Business in Canada?
You should consider incorporating once your business faces real liability risk, generates steady profit, or plans to bring on partners, investors, or employees. Waiting too long can leave your personal assets exposed during your most vulnerable growth years.
There is no single magic number that triggers the right time to incorporate. However, several signs suggest the moment has arrived:
- Your business income consistently exceeds what you need for personal living expenses.
- You are signing contracts, leases, or agreements with real financial consequences.
- You employ staff or contractors, which increases legal and liability exposure.
- You want to reinvest profits into the business at a lower corporate tax rate.
- You plan to seek investment, sell the business someday, or bring on a business partner.
On the other hand, a very small side business with minimal risk and income may not need incorporation immediately. In this case, weigh the setup and compliance costs against your actual exposure.
What Is the Best Business Structure for Asset Protection in Canada?
For most growing businesses, incorporation offers the strongest asset protection available in Canada. Adding a holding company structure can provide an extra layer of safety once the business accumulates significant profit or assets.
That said, “best” depends on your specific situation. A single consultant with low liability risk may be fine as a sole proprietor for a while. In contrast, a contractor, retailer, or manufacturer facing regular customer contact and financial risk should incorporate sooner rather than later.
Professionals such as doctors, lawyers, and accountants often use professional corporations, which have their own specific rules set by provincial regulatory bodies. These structures offer tax benefits but may have limited liability protection for professional negligence claims, since professionals typically remain personally liable for their own malpractice.
Asset Protection Strategies for Incorporated Business Owners
Incorporation is a strong first step, but it is not the finish line. Successful business owners layer several strategies together for stronger, long-term protection.
- Use a holding company to move surplus profits out of the operating company, reducing what creditors can claim if the operating business runs into trouble.
- Carry proper insurance, including commercial general liability and, where relevant, professional liability or director and officer insurance.
- Avoid unnecessary personal guarantees whenever possible, and negotiate limits when guarantees are required.
- Separate high-risk assets, such as real estate, into their own corporation rather than holding them inside the main operating business.
- Review shareholder agreements regularly, especially as new partners or investors join the business.
- Work with a lawyer and accountant together, since asset protection touches both legal structure and tax planning.
Manager’s Checklist: Protecting Your Personal Assets
Quarterly Asset Protection Self-Check
- Have I kept business and personal bank accounts completely separate this quarter?
- Have I signed any new contracts or leases? If so, did I sign as the corporation, not personally?
- Is my corporate minute book updated with recent decisions and resolutions?
- Have I filed my annual corporate return on time?
- Does my insurance coverage still match my current level of business activity?
- Have I reviewed whether a holding company now makes sense for my accumulated profits?
- Have I avoided any new personal guarantees, or clearly understood the risk of ones I signed?
Running through this checklist every few months helps catch small gaps before they become expensive problems.
Frequently Asked Questions
Which business structure offers the most protection for personal assets?
Incorporation generally offers the most protection for personal assets in Canada. Adding a holding company structure can further protect accumulated wealth from operating business risks, especially as the company grows.
Does incorporating in Canada actually protect personal assets, or only under specific conditions?
Incorporating protects personal assets, but only when you maintain proper corporate formalities. If you mix funds, sign personal guarantees, or ignore filing requirements, courts may still hold you personally liable.
How does an incorporated business differ from an LLC for Canadian entrepreneurs?
Canada does not offer an LLC structure like the United States. Instead, Canadian entrepreneurs incorporate as a corporation, which is taxed and regulated differently than a US LLC under Canadian corporate and tax law.
What is the best way to protect my assets as a business owner?
The best approach combines incorporation, separate finances, proper insurance, and careful contract management. In addition, reviewing your structure regularly as your business grows helps close gaps before they become costly.
What ongoing steps are needed to maintain asset protection as a business grows?
You need to keep filing annual returns, separate personal and business finances, update your minute book, and review your insurance and corporate structure regularly. Growing businesses often benefit from adding a holding company for extra separation.
Key Takeaways
- A sole proprietorship leaves your personal assets fully exposed to business debts and lawsuits.
- General partnerships carry added risk, since you can be liable for your partner’s mistakes.
- Incorporation creates a legal separation between you and your business, but this protection is not automatic or permanent.
- Courts can pierce the corporate veil if you mix funds, commit fraud, or ignore corporate formalities.
- Personal guarantees on loans or leases can undo incorporation’s protection, regardless of your business structure.
- A holding company can add an extra layer of protection as your business accumulates profit and assets.
- Asset protection is an ongoing process, not a one-time decision made at startup.
Choosing the right business structure is one of the most important financial decisions you will make as a Canadian entrepreneur. A sole proprietorship might feel simple today, but it could put your home and savings at risk tomorrow. Incorporation offers stronger protection, though it requires discipline to maintain over time.
If you are unsure whether your current structure truly protects you, now is the time to find out. Consider working with a qualified lawyer and accountant to review your corporate structure, your contracts, and your growth plans together. A proactive review today can prevent a painful, expensive lesson down the road.
Legal Disclaimer
The information in this article is provided for general informational purposes only and is not legal advice. No content here shall be interpreted as implying that Dimitrov Law Professional Corporation or Atanas Dimitrov are the best or superior to any other lawyers or law firms. For guidance related to your specific situation, please contact a qualified professional.
Message us here with any questions OR visit our website: https://dl-pc.ca/.